The main types of digital payments, and how to offer financial services using them
With the increasing use of electronic devices, such as smartphones, computers, and other devices, digital payments are gaining traction in the financial arena, revolutionizing how transactions occur.
Among the advantages of using digital payment methods, we can mention convenience, speed of processing, security, and low operating costs. It's no wonder that, as we will see below, these payment options have become increasingly popular and preferred by both consumers and businesses worldwide.
In this article we analyze the main types of digital payments, and delve into how offering financial services with these types of payments has become essential for companies and financial institution to meet their clients’ needs.
What are digital payments?
Digital payments are financial transactions that are performed completely online. Payments occur through a simple virtual transaction from a device such as a smartphone, tablet, smartwatch, or computer.
The principal characteristic of a digital payment is that, contrary to more traditional forms of payment, there is no need to have a physical element, such as cash.
That's precisely why digital payments offer the payer the convenience of making the transaction regardless of their location , while the payer has the assurance that the payment has actually been made.
Accelerated adoption of digital means of payment
It is a fact that the coronavirus pandemic acted as a significant catalyst in the widespread adoption of digital payments. After all, as concerns about safety and social distancing increased, both consumers and businesses began to prioritize contactless payment methods.
In Latin America, according to Global Findex 2021 , 40% of adults made digital payments at a commercial establishment during the pandemic, including 14% who did so for the first time.
During the pandemic, 15% of adults paid their public utilities through digital transactions for the first time, which is more than twice the average of developing countries.
The same study highlights that opportunities exist for even greater use of digital payments , given that 150 million adults with bank accounts made payments at commercial establishments using only cash during the pandemic, including more than 50 million in Brazil and 16 million in Colombia.
Read also | Tokenization: what is it and what is its impact on financial services?
The most important digital means of payment in Latin America
The accelerated use of digital payments has profoundly redefined the manner in which we receive and conduct financial transactions.
As new financial solutions enter the market, we see a growing consumer preference for faster, more secure, and convenient payment methods . Below, we list some of the most relevant digital payment services among Latin Americans.
Instant payments
Instant payments are a type of digital payment that allows amounts to be sent in real time from one account to another. Everything happens in seconds, without middlemen: the transaction occurs through applications, sites, or digital wallets.
Currently more than 50 countries work with instant payment systems. Thanks to Pix, Brazil ranked second in the number of this type of transaction in 2022, trailing only India, according to Prime Time for Real-Time Report, released by the Central Bank of Brazil.
In Latin America, the level of adhesion to instant payment is in different stages in the six countries with the highest GDP on the continent: Argentina, Brazil, Chile, Colombia, Mexico e Peru. On one end of the spectrum is Brazil, with its success implementing Pix. On the other end is Chile, with promises to set up a similar type of system, but without technological progress in recent years.


There is enormous potential for instant payments in Latin America, since, in 2023, 21% of Latin American adults – or 91 million consumers – rely exclusively on cash, according to a study by Mastercard and Americas Market Intelligence (AMI).
Cards
Credit and debit cards are also popular means of digital payment in Latin America. With the evolution of technology, payments can now be made completely online, by cell phone, and contactless (tap).
In 2020, credit cards were the most used payment method for e-commerce purchases in Latin America , accounting for 59% of transactions.


While 58% of Latin Americans have a credit card, only 31% have access to a loan or line of credit, 28% to individual insurance, and 21% to other investments, according to the Mastercard / AMI study.
Read also | Credit market in Latin America: 4 opportunities to boost the sector
Payment link
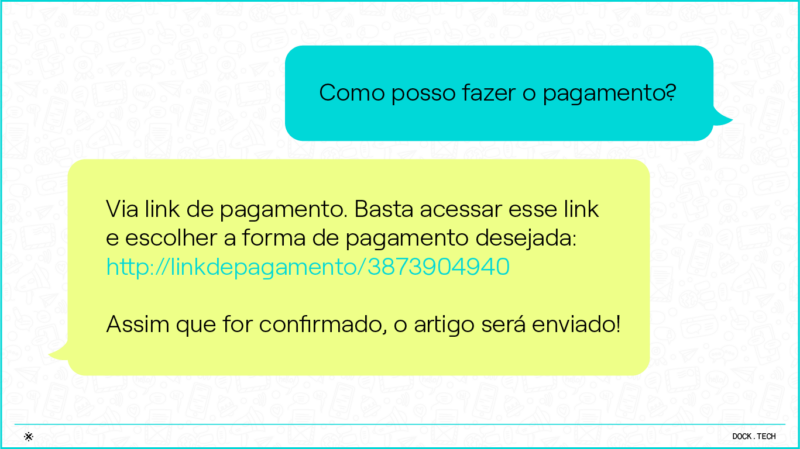
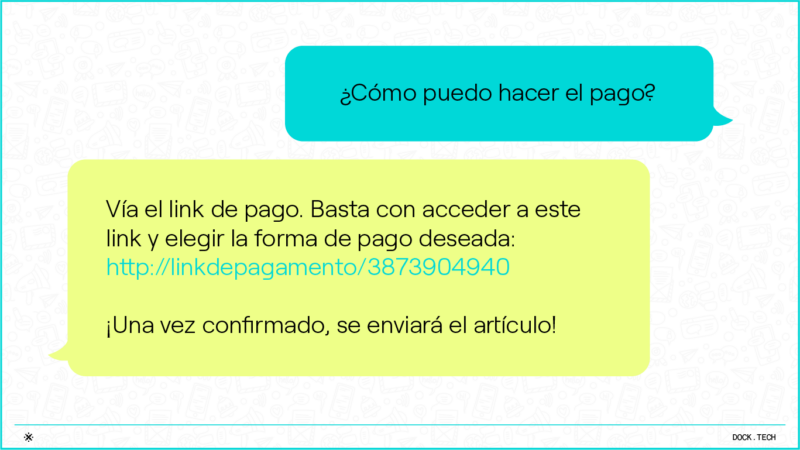
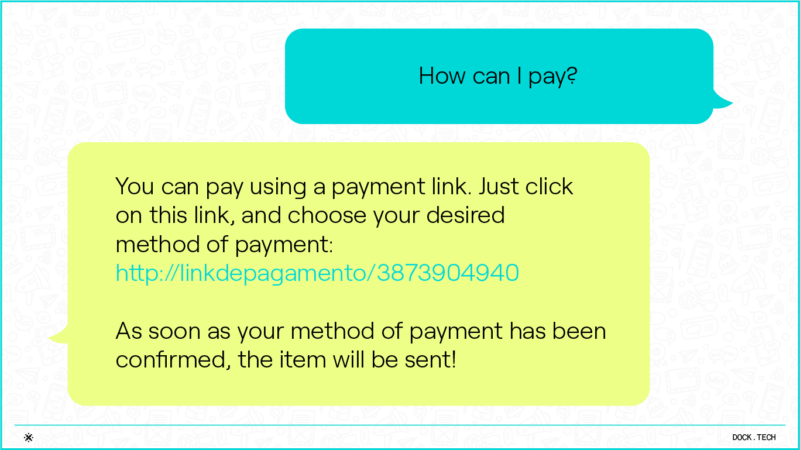
A payment link is an electronic address generated by a platform that provides this service. Through the platform, the issuer registers the product, amount, and number of installments, and the system generates a link.
This link may be shared by text message, social network, or e-mail, taking the client to a page with the details of the financial transaction, such as amount and description. There, the client inputs their payment information, and after confirmation, the transaction is concluded.
Because of how easy it is to use, its low cost, and reduced attrition at checkout, the tool is a versatile solution that can be used by small, medium, and large companies, shortening steps in the online sales process.
Digital wallets
Many people confuse a digital wallet with a digital account; however, they are different means of payment. A digital wallet is a type of application in which the user can add a balance of funds and link their cards, allowing them to make purchases using just their smartphone. That is, it does not necessarily have to be linked to a financial institution.
In 2020, according to research by Visa Consulting & Analytics , 12% of Latin Americans already used digital wallets as their preferred method of payment , demonstrating that so-called consumer-centric payments are becoming a trend.
McKinsey's Digital Payments Survey 2022 indicates that more than two-thirds of Americans expect to have a digital wallet within two years, and many are likely to own multiple wallets. Furthermore, the percentage of consumers who intend to use three or more digital wallets in the coming years rose from 18% in 2021 to 30% in 2022.
Trends in digital payments
There is no doubt that digital payments are the focus of attention for consumers and, consequently, for companies that offer financial services and products.
According to the New Payments Index 2022 , 74% of Latin Americans pay their bills online and 19% plan to do so in the future. Similarly, the aforementioned McKinsey research reveals that the percentage of consumers using digital payments jumped impressively from 51% in 2021 to 62% in 2022.
Against this backdrop, we can confirm that digital means of payment are trending upwards.
Crypto Payments
Cryptocurrencies are gaining ground as a means of payment. These are called Crypto Payments.
Research by CoinsPaid, conducted in Brazil, Colombia, and Argentina, shows that 41% of people have a better perception of a business when it accepts payments in digital currencies.
El Salvador, the first country to implement Bitcoin as legal tender, is leading the way in Crypto Payments in Latin America. Other countries are also taking steps to facilitate the use of cryptocurrencies in different sectors and at different companies.
Buy Now Pay Later
Known by the acronym BNPL ( Buy Now Pay Later ), "buy now, pay later" refers to a category of payment solutions that, as the name suggests, allows customers to buy something now and pay for it in the future.
Most of the time this model applies to purchases made online that can be paid for in a single payment, or in installments without interest on short-term financing.
The main reasons for using BNPL are its ease of use and convenience, especially because there are no lengthy credit checks and the method is fully integrated into the purchase journey and checkout experience.
Cross Border Payments
A Cross Border Payment is a financial transaction that occurs between two parties located in different countries.
Although this transaction might look simple, there are several factors impacting the process, such as currency conversion, service fees, and taxes. Cross Border payment solutions help make this procedure simpler and more flexible.
According to BIS International , banks all over the world recorded a US$ 782 billion increase in this type of transaction in the second half of 2022, which is annual growth of 8% compared to the prior year.
Read also | International money transfer: what motivates the expansion of this financial service?
Digital payments and financial inclusion
Digital payments drive financial inclusion by providing access to financial services to a wider segment of the population. By eliminating geographical barriers and reducing costs , they allow individuals in remote regions and unbanked populations to conduct transactions conveniently and securely.
A survey by the Central Bank of Brazil , for example, shows that the growth in the use of digital payments in Brazil, which has been on the rise in recent years, has resulted in a reduction in the number of unbanked individuals.
The study shows growth of 14% between 2017 and 2021 in the number of adults with bank accounts in Brazil, with 84% of respondents indicating they had an account in 2021. Considering only the poorest 40%, the numbers rose from 57% of respondents in 2017, to 82% in 2021.
How to offer solutions with digital means of payment using Dock’s technology
Dock One is Dock’s payments and banking platform that was created to be a modern, secure, and efficient technological solution for any institution and company interested in offer digital payment services as part of their growth strategy.
Integrated and in constant evolution, Dock One is fully API-based, operating on four main fronts:
- Banking: offer your clients a complete digital account with access to the most-used financial services.
- Cards & Credit: structure a flexible credit, debit, and pre-paid card operation.
- Acquiring: simplifies business management with processing, software updates, and real-time monitoring.
- Fraud Prevention: state-of-the-art fraud management technology that identifies and prevents fraud at all stages of the transaction.
When you choose Dock One, your company has access to the most modern and secure financial services, with a very fast time to market. And best of all, there is no need for costly investments or long waiting times to develop and manage new solutions. Learn more:
Digital payments: what you saw in this article
- Digital payments are financial transactions that take place completely online, using devices such as smartphones, tablets, and computers.
- Some of the advantages of using digital means of payment are convenience, quick processing time, security, and low operating cost.
- Instant payments, cards, digital wallets, and payment links are some of the most popular digital means of payment in Latin America.
- Crypto Payments, BNPL, and Cross Border Payments are some of the trends in digital payments.
- There are even greater opportunities for digital payments, as 150 million adults with a bank account paid merchants using only cash during the pandemic.
Related articles:
-
- Bioeconomy: what does it have to do with banks and fintechs?
- Febraban Tech 2023: the top seven subjects discussed at the largest financial event in Latin America
- Payroll Fintechs and the corporate benefits market: advantages and new opportunities
- Simplifying accounting through Embedded Finance | An interview with Contabilizei
 Enrollment done!