Embedded Finance: The phenomenon turning companies into ‘banks’
In the past few years, we’ve seen deep changes in the financial industry, while also becoming familiar with concepts and trends that are essential for that entire transformation based on decentralization, emerging new players and financial inclusion. Among those movements, we have Embedded Finance.
To put it simply, we can say that this is the phenomenon that transforms companies into banks. Through Embedded Finance, any business has the possibility of adding financial products and services to its portfolio without neglecting its core business.
If you've ever used a store credit card , for example, it was most likely an Embedded Finance experience. In other words, this dynamic is already part of our daily lives, making financial services easier to use, more convenient, and more personal.
To explain in more detail what this phenomenon is and how it is revolutionizing the distribution of financial services, we spoke with Bruno Diniz , an expert in innovation in the sector, co-founder of Spiralem , South America Director at FDATA (Financial Data & Technology Association), professor at Fundação Dom Cabral and the USP MBA program, and author of the book "The Fintech Phenomenon". Check out our conversation below.
Watch the video summary and check out the interview in full!
For starters, what is Embedded Finance?
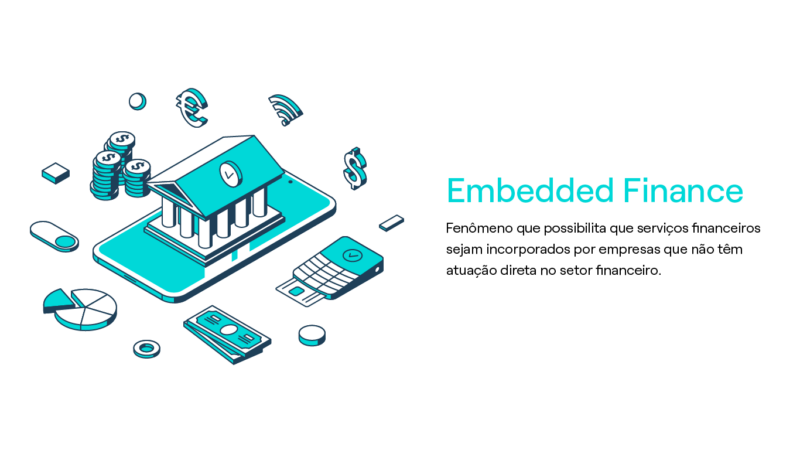
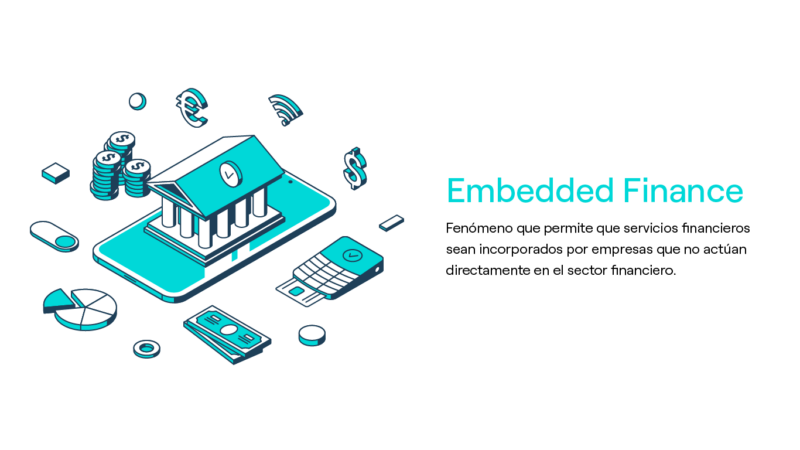
Bruno Diniz: The literal meaning of Embedded Finance is "embedded finance" or " embedded finance ." So, basically, this concept refers to giving companies that don't necessarily operate in the financial sector the ability to distribute financial solutions . Its objective is to enable them to operate in the segment and offer financial products and services to their customer and user base.
Therefore, Embedded Finance is related to this transformation of the financial market, which is causing the dividing line between the "traditional" financial service provider and the new providers—which are neither banks nor fintechs —to become increasingly blurred.
We have all types of companies, from have retail to technology and phone companies, taking part of that movement and starting to explore that field. At the same time, the technological and regulatory barrier is diminishing, and new service providers in Banking as a Service are emerging by enabling that opportunity.
What types of financial products can be embedded by those companies?
Bruno Diniz: Products such as digital wallets , checking accounts, digital accounts , credit, insurance , loans, and other services.
Also, we’ve expanded that range to a number of different solutions under the Embedded Finance umbrella—such as Embedded Fintech e Embedded Insurance.
Apart from financial gains, what are the advantages for companies embedding financial services into their ecosystem?
Bruno Diniz: The financial gain is certainly one of the main advantages of Embedded Finance, as you benefit both from the monetization you will have with your clients, and from the "independence" from banks for operations such as paying salaries or suppliers without going through these institutions.
But that's not all: another great advantage is the possibility of creating a robust ecosystem of solutions capable of keeping the customer closer to you.
Let’s take a retailer as an example. By adding financial solutions, they have a great opportunity to bank their consumers. Besides, they can also partner with different companies—such as car service or delivery app—and start providing them with a wider range of solutions. That becomes attractive to clients, since they’ll find solutions for different aspects of their lives.
What are the facts enabling this emerging and evolving trend of Embedded Finance at the moment?
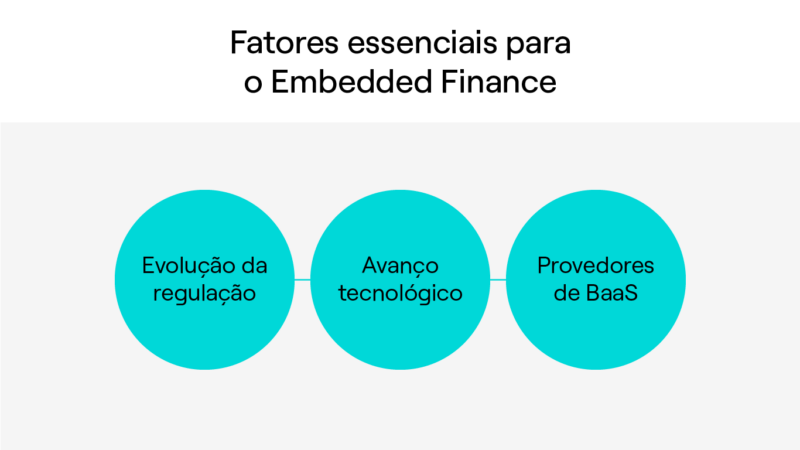
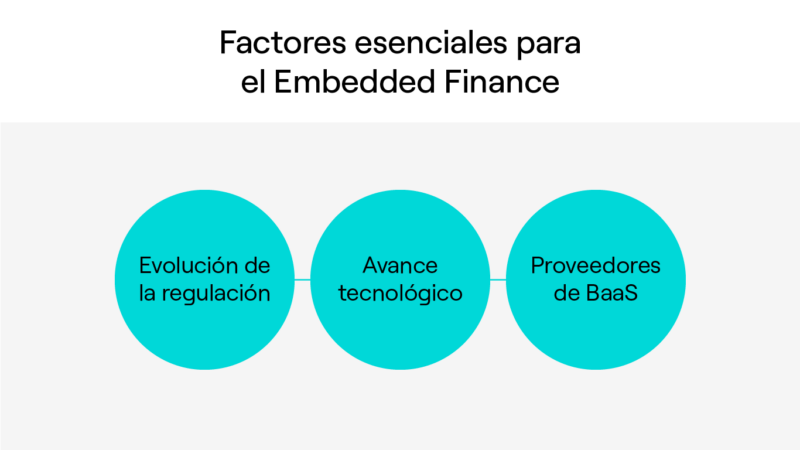
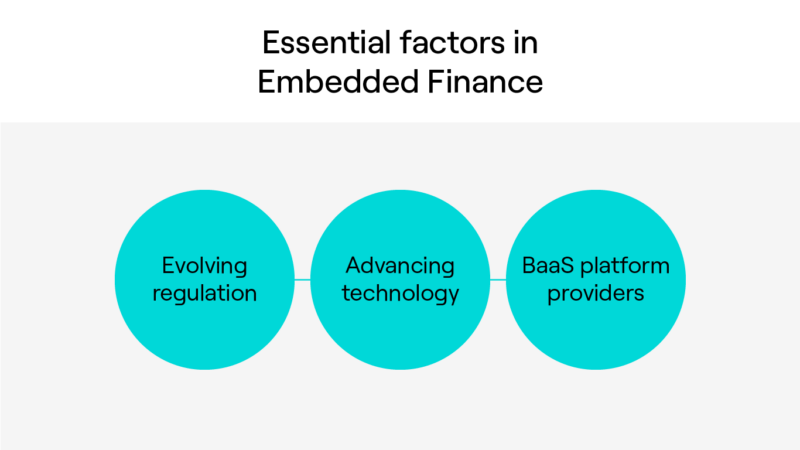
Bruno Diniz: There are three factors that allowed us to arrive at Embedded Finance. The first concerns the evolution of regulation. If we look at the financial market from twenty years ago, we didn't have so many new entrants. It was much more closed in terms of the provision of financial services and was limited to a few institutions. Over time, the Central Bank opened up competition and created different possibilities to actually encompass these new entities.
The second point concerns the technology itself , which has become more accessible. Twenty years ago, setting up a digital operation required a lot of resources. This made the necessary infrastructure extremely expensive for anyone wanting to enter the game.
Finally, the third one is about emerging service providers in Banking as a Service, which master that expertise from a regulatory and technological standpoint. So they can put all that into practice in order to enable that transformation.
Therefore, today it's easier than ever to create a digital bank or embed financial solutions into your business. But if you try to do this with the structure you have in-house, the difficulty will be immense. Having the support of established companies that know the ropes and have numerous successful cases under their belt will make all the difference in leveraging your operation.
How does Embedded Finance help financial inclusion in Brazil and other countries in Latin America?
Bruno Diniz: For a long time in Latin America, we had few options for financial institutions and low competition, with very similar fees charged.
Now, we are seeing a massive entry of players into the financial market. This has been gradual: five or eight years ago, fintechs were beginning to emerge as competitors. However, they had to climb the ladder to become big enough to compete with the big institutions.
With Embedded Finance, now we have more momentum. Today different established companies start providing financial services in our region, which enables a wider range of alternatives.
Furthermore, this transformation brings the possibility of financial inclusion for many people who were not of commercial interest to banks. As a result of this change, they can now use financial services, also because these new players have a different understanding of this consumer profile.
That’s why today the friction for someone to have their first account or start having access to products of that kind is significantly diminishing. You might not be banked, but you somehow leverage some non-financial solution offered by some company.
The entry of these new institutions from other sectors into the financial market represents a major step forward in terms of inclusion and financial access in Latin America.
What is the connection between Embedded Finance and two recent regulatory milestones in Brazil: Pix and Open Banking?
Bruno Diniz: O Pix manages to bring another layer of leveling between the institutions that participate in this market, coming as an element that helps to give more strength to this package of offers that become possible in this new reality of Embedded Finance.
Likewise, the Open Banking it's one of those layers. By making it possible for customer data to circulate among the institutions authorized to participate in this environment, he manages to unlock all this potential even more.
If you're a player outside the financial sector, a delivery app for example, you already have a much better understanding of your target audience. Let's say you're offering financial products to restaurants. You'll understand seasonality, know who has a good market share, and how that would impact those who have to repay a loan.
O Open Banking concerns the empowerment of citizens in relation to their own data. It's about how I can give up my data to obtain benefits from it. This integrated environment with new agents using this to leverage opportunities is one of the best possible scenarios for inclusion and personalization of financial offers.
What countries are most advanced and have the greatest potential for Embedded Finance?
Bruno Diniz: We have some very interesting cases in the United States. Looking at those that can have the greatest impact thanks to Embedded Finance, I can't help but mention the Big Tech companies that are adding financial services and products.
Amazon is one of them: the company is increasingly establishing itself in this market and has great potential. In its core business, which now also has an entertainment division, already offers solutions for different pains. So, before you know it, you're already totalmente immersed within the ecosystem created by Amazon.
However, I also think that the Embedded Finance movement will help to include players from very specialized niches. Here in Brazil, for example, we already have solutions aimed at recyclable material collectors. Now we will start to see more and more solutions appealing to specific niches , such as freelancers, truck drivers, etc. Thus, different people will benefit from this phenomenon.
Does Embedded Finance bring any risk for companies or the financial system itself?
Bruno Diniz: I don’t think so, also because This entire movement is supported by all possible legal foundations. Therefore, if this is being made possible, the companies that provide Banking as a Service will be paying close attention. That’s why I don’t see risks or issues.
Also, I believe that is kind of a myth we need to shatter. After all, the more alternatives we have on the market, the better. And, if the market today allows us — both for technological and regulatory reasons — to have these new alternatives, this is quite healthy for us to have greater inclusion and more possibilities of choice within the market.
Land of opportunity: The numbers in Embedded Finance
After reading this interview , it's clear that Embedded Finance is advancing by leaps and bounds. The landscape presents many opportunities for companies wishing to begin embedding finance into their businesses, as some projections demonstrate:
- A Finnovista estimates that the global opportunity for that service mode should reach over US$ 7 trillion within ten years—a value 30x higher than the total from XNUMX major banks in the world.
- For Latin America, the international research institute Research and Markets expects the revenue for the embedded finance market to grow by 27% by 2029, reaching 13,7 billion dollars by the end of that period.
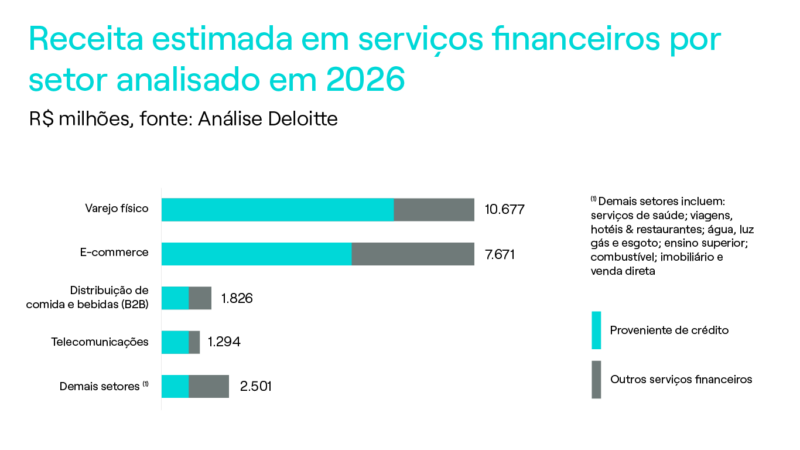
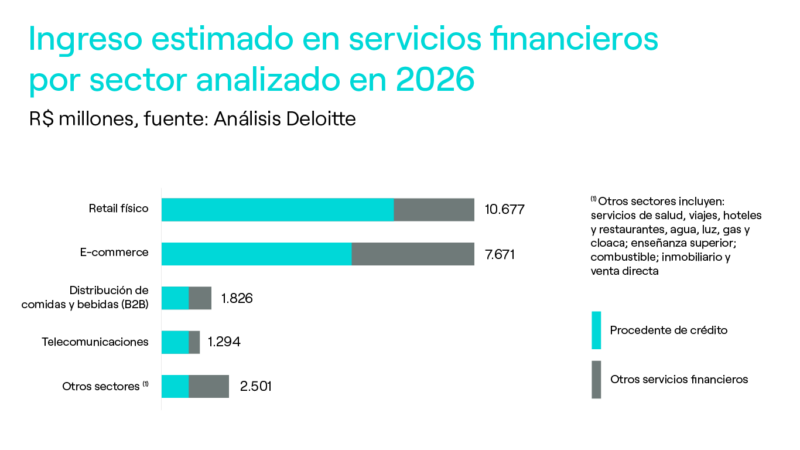
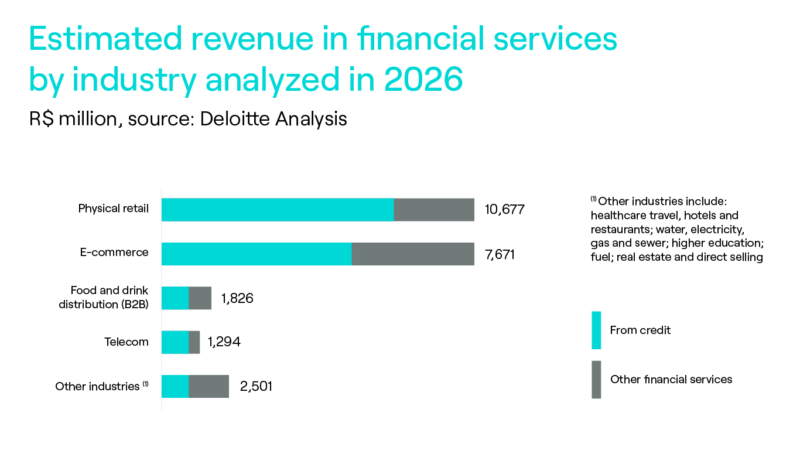
- According to a study conducted by Deloitte, Brazilian industries—such as retail, consumer goods and more services contributing to over 35% of the GDP—will be able to expand their financial product and service offering and capture R$ 23 billion a year within five years.
Main features of Embedded Finance
As we mentioned, Embedded Finance allows the integration of financial services into non-financial platforms, making the user experience more fluidae convenient. This approach eliminates the need to access external banks or applications, providing faster and more intuitive transactions. Check out its main features:
- Financial services integration: allow that marketplaces, applications and e-commerces offer financial services, without the user needing to leave the platform.
- More convenience for users: By allowing customers to access other services directly from the platform they are using, Embedded Finance makes the journey more convenient.
- Connection between systems via APIs: This means the possibility of incorporating financial solutions without having to develop an infrastructure from scratch, reducing costs and accelerating implementation. APIs also allow for scalability, allowing financial services to be adjusted according to business growth and user demand.
- Improved User Experience: By reducing steps and simplifying processes, Embedded Finance provides a more intuitive and cohesive experience, making financial services a natural extension of the user's digital journey.
What is the difference between Embedded Finance and BaaS?
Embedded Finance and Banking as a Service (BaaS) are interconnected, but distinct concepts and have different purposes.
BaaS functions as the technological foundation , the infrastructure that enables Embedded Finance, allowing companies to offer financial services without needing a banking license. Embedded Finance, on the other hand, focuses on the user experience , incorporating payments, credit, and insurance directly into non-financial platforms, such as marketplaces and mobility apps.
While Embedded Finance enhances the consumer journey by making financial services more accessible and intuitive, BaaS empowers companies to develop tailored financial solutions . This allows businesses across various sectors to integrate banking products without significant infrastructure investments, expanding their offerings and increasing customer engagement.
How important is embedded finance for the financial services sector?
The finances on board are transforming the financial sector by allowing banking services to be integrated directly into different platforms, making transactions more fluidas and accessible.
Banks, fintechs and companies from different segments can offer personalized financial solutions without customers having to resort to other institutions, improving retention and expanding their reach.
In addition to convenience, this approach strengthens security and prevention of fraudes, ensuring greater reliability for digital transactions. Below, see how embedded finance drives innovation and benefit the financial sector as a whole.
Customer experience improvement
This results in greater satisfaction and loyalty, as the customer can access financial services directly where they already carry out other transactions, without needing to resort to another bank or platform.
New Revenue Streams
The incorporation of financial services creates new revenue streams , as institutions can charge fees or commissions for providing solutions such as payments, loans, and other financial products. It's also possible to monetize offerings through partnerships and integrations with companies in other sectors.
Expansion of distribution channels
Embedded Finance offers an effective way to expand distribution channels for financial services. By forming partnerships with companies in various segments, such as e-commerce and mobility platforms, institutions can reach new audiences and increase their reach.
Customization of services
With access to customer data, embedded finance enables institutions to personalize their products and services, offering more accurate and targeted solutions. This strengthens customer relationships as offers are more relevant, increasing the chances of conversions and improving profitability.
Innovation and agility
The adoption of embedded finance allows institutions to be more agile and innovative . They can launch new products and services more quickly, responding immediately to market needs and taking advantage of growth opportunities, without the limitations of traditional structures.
What main business models can work with Embedded Finance?
Various business models can benefit from Embedded Finance, making financial services more accessible and convenient for users.
E-commerce platforms can offer integrated payment methods and direct credit options on their platforms, while marketplaces enable safer and faster transactions between sellers and buyers. Mobility platforms , such as ride-hailing apps, can incorporate digital wallets and insurance, improving the user experience.
Sectors such as retail, tourism, education, and even healthcare can also explore Embedded Finance, offering installment plans, insurance, and automatic payments.
It is worth remembering that, when using the Banking as a Service, companies can integrate financial solutions without the need to become banks, which provides flexibility for different segments.
Embedded Finance is part of our project for decoding the financial universe, driving businesses and transforming society
Na Dock, our goal is to decode the financial universe, boost business and transform society. The concept of Embedded Finance that we explore in this article is part of how we provide cutting-edge solutions so that players from different segments can offer financial products and services to their customers.
From retail to manufacturing, companies of a variety of industries and sizes can benefit from the Embedded Finance phenomenon. And here at Dock, we’ve supported a number of companies in driving their business and accelerating financial inclusion through embedded finance.
Discover the stories of some of our clients who are making finance organic and transforming society.
FAQ: see respostas for the main questions about Embedded Finance
What is Embedded Finance?
The expression is used when financial services are incorporated into areas that are not directly related to the financial world. In sum, it is a phenomenon turning companies into banks.
Is Embedded Finance an opportunity exclusively for retail?
Retailers across the world, especially in Latin America, already see Embedded Finance as an old acquaintance. No doubt the industry was a pioneer—and why not a visionary—in adopting embedded finance in their business model.
However, the Embedded Finance phenomenon is currently experiencing a new phase, with more and more companies from different sectors participating in this transformation.
That’s why offering financial services and products can be a strategy adopted by companies in the B2C as well B2B industry.
What are the advantages for companies adopting Embedded Finance?
Companies that adopt Embedded Finance can obtain benefits such as creating an alternative source of revenue, building customer loyalty , reaching new consumers, increasing the average transaction value , and gaining a competitive advantage.
It is worth mentioning that the benefits in Embedded Finance go beyond the corporate world, positively impacting users and the means of payment and banking as well as society as a whole.
Embedded Finance: what you saw in this article
- Embedded Finance enables companies (which are not traditional players in the financial industry) to work in the segment and add financial services and products to their offering portfolio.
- Services that can be part of Embedded Finance include digital wallets, digital accounts, credit, loans and insurance plans.
- By reducing barriers for new players to join the industry, Embedded Finance contributes to financial inclusion.
- Pix and Open Banking are regulatory milestones in Brazil that build even more momentum for growing Embedded Finance in the country.
- From retail to manufacturing, companies of a variety of industries and sizes can benefit from the Embedded Finance phenomenon.
Related articles
- Web3: Understand what it is and the changes it can bring the financial industry
- Agritech: 5 opportunities for innovating in agribusiness by relying on financial solutions
- Financial inclusion in Latin America: The scenario and opportunities for fintechs
- Financial inclusion and fraud prevention: How does security in payments contributes to new advances?
 Enrollment done!